HDFC Marriott Bonvoy Credit Card vs IDFC FIRST Ashva Credit Card
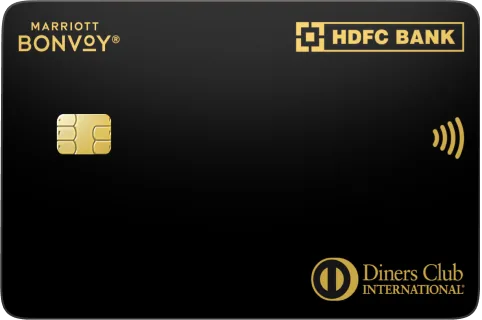 HDFC Marriott Bonvoy Credit Card |
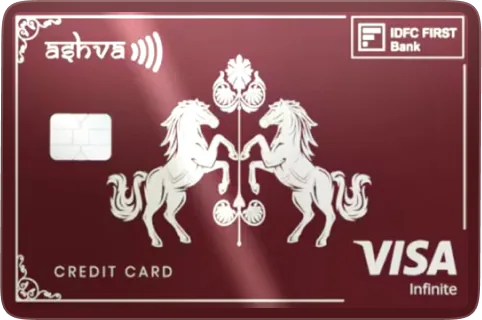 IDFC FIRST Ashva Credit Card |
|
| Bank |  HDFC Bank |  IDFC FIRST Bank |
| Card type | Shopping | Shopping |
| Joining fee | ₹3,000 | ₹2,999 |
| Annual fee | ₹3,000 | ₹2,999 |
| Fee waiver | The annual fee is not waived under any spending conditions. | The annual fee is not waived under any spending conditions. |
| Welcome benefit | The ₹3,000 + GST joining fee is effectively offset by welcome benefits such as a Free Night Award (up to 15,000 points) and Silver Elite status with 10 Elite Night Credits, delivering upfront value that can match or exceed the joining fee for Marriott users. | Joining fee is offset through 2,500 reward points on payment of the joining fee. |
| Reward point value | 1 Reward Point = ₹0.25 | 1 Reward Points = ₹0.25 |
| Airport lounge | Enjoy 12 Domestic + 12 International Airport Lounge | Enjoy 4 complimentary Domestic Airport Lounge |
| Card network | VISA | VISA |
| Minimum income | ₹12 lakh a year | ₹12 lakh a year |
| Credit score | 750+ | 750+ |
| Best for | Shopping, Airport Lounge, Dining, Travel | Shopping, Travel |
| Benefits | Earn 8 Marriott Bonvoy Points per ₹200 at Marriott Hotels | Earn up to 40 Reward Points per ₹150 on Hotel Bookings |
| Earn 2 Marriott Bonvoy Points per ₹200 on Other Spends | Enjoy 4 complimentary Domestic Airport Lounge | |
| Enjoy 12 Domestic + 12 International Airport Lounge | Up to 10X Reward Points | |
| Earn 4 Marriott Bonvoy Points Per ₹200 | Enjoy 0% Forex Markup | |
| Complimentary Marriott Bonvoy Silver Elite Status | Earn 7,500 Reward Points Worth up to ₹3,000 | |
| Complimentary Golf Access Worldwide | Enjoy 2 complimentary International Airport Lounge | |
| Apply | Apply |
Key differences
- Both cards include airport lounge access: HDFC Marriott Bonvoy Credit Card – Enjoy 12 Domestic + 12 International Airport Lounge; IDFC FIRST Ashva Credit Card – Enjoy 4 complimentary Domestic Airport Lounge.
- IDFC FIRST Ashva Credit Card offers low forex markup; HDFC Marriott Bonvoy Credit Card does not list it.
Pros and cons
Which card should you choose?
Choose HDFC Marriott Bonvoy Credit Card if you are one of the people who shop online often and want extra value on their favourite apps.
Choose IDFC FIRST Ashva Credit Card if you are one of the people who shop online often and want extra value on their favourite apps.
Not sure? Try the card finder or talk to an expert for free.
Frequently asked questions
Which is better, HDFC Marriott Bonvoy Credit Card or IDFC FIRST Ashva Credit Card?
IDFC FIRST Ashva Credit Card is cheaper to keep (₹2,999 vs ₹3,000 per year). Both are shopping cards, so the better pick depends on where you spend most.
Which card has the lower annual fee?
IDFC FIRST Ashva Credit Card is cheaper to keep (₹2,999 vs ₹3,000 per year).
Which card gives airport lounge access?
Both do. HDFC Marriott Bonvoy Credit Card: Enjoy 12 Domestic + 12 International Airport Lounge. IDFC FIRST Ashva Credit Card: Enjoy 4 complimentary Domestic Airport Lounge.
What income do I need for these cards?
HDFC Marriott Bonvoy Credit Card: about ₹12 lakh a year. IDFC FIRST Ashva Credit Card: about ₹12 lakh a year.
Can I apply for both cards?
Yes. They are issued by HDFC Bank and IDFC FIRST Bank. Each bank checks your eligibility separately.
More comparisons
Details last updated 4 Oct 2026. Banks change fees and features from time to time, so please check the final terms on the bank's page before you apply.